Market Report ·
🌍 DELTANODE | WEEKLY MACRO & MARKET OUTLOOK NOV 1/ 2026
Markets enter November facing a heavy week of central-bank decisions, US midterm elections, employment data and major technology earnings. Last week, the Fed held rates despite two dissenting votes, inflation remained elevated, and rising AI infrastructure spending continued to put pressure on technology valuations.
The key question this week is whether economic growth and employment remain strong enough to justify further monetary tightening. Meanwhile, Treasury yields, central-bank guidance and political uncertainty could drive volatility across equities, bonds and crypto.
━━━━━━━━━━━━━━━━━━
📊 1. LAST WEEK: WHAT HAPPENED?
🏦 Federal Reserve: Rates Held at 3.75%–4.00%
The Fed kept interest rates unchanged in a 10–2 vote. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favour of a rate increase.
The statement added that more economic information would help determine the future policy stance. Chair Kevin Warsh described the internal disagreement as a family fight.
Despite the hold, futures continued pricing approximately an 85% probability of a rate increase at the December 9 meeting.
Market implication: The Fed remains concerned about inflation. A rate cut is not necessarily the next move, and further tightening remains a possibility.
📈 US GDP & PCE Inflation
US Q3 GDP came in at 3.4%, above the 3.2% consensus estimate.
Inflation remained elevated: • Headline PCE: 3.6% • Core PCE: 3.1% • Personal saving rate: 3.8%, down from 4.0% • Employment Cost Index: +0.8% in Q3
The next major labour-market indicator is Friday's US October employment report.
Market implication: Economic growth remains resilient, but persistent inflation makes the Fed's job more difficult.
💻 Big Tech Earnings: AI Spending Under the Microscope
Major cloud businesses continued to report strong growth:
• Google Cloud: +103%, reaching $30.71 billion. • Microsoft Azure: +48%. • Amazon AWS: +39%, reaching $45.98 billion.
However, capital expenditure raised concerns:
• Alphabet quarterly capex: $51.36 billion. • Amazon quarterly capex: $77.26 billion. • Amazon's trailing 12-month free cash flow fell to -$42.4 billion.
Alphabet finished October down 17.22%, while Microsoft gained 1.78%. The Nasdaq declined 5.30% during October, its worst monthly performance since March 2025.
Market implication: Investors are increasingly demanding evidence that AI infrastructure investments will translate into sustainable earnings and cash flow.
🇬🇧 UK Autumn Budget
Chancellor John Healey increased the bank surcharge from 3% to 6% for 15 months.
Fiscal headroom against the government's rules fell to £14.5 billion from £23.6 billion. Despite the reduced fiscal buffer, the gilt market reacted relatively calmly.
The Bank of England's policy decision is now the next major UK catalyst.
📉 US Market Performance
Friday's closing figures:
• S&P 500: 7,580.07, down 1.82% on Friday and 0.6% for the week. • Nasdaq: down 2.0% for the week. • Both indices recorded their third consecutive weekly decline. • US 10-year Treasury yield: 4.93%. • US 2-year Treasury yield: 4.59%.
Several Fed officials also indicated that further rate increases remain possible.
━━━━━━━━━━━━━━━━━━
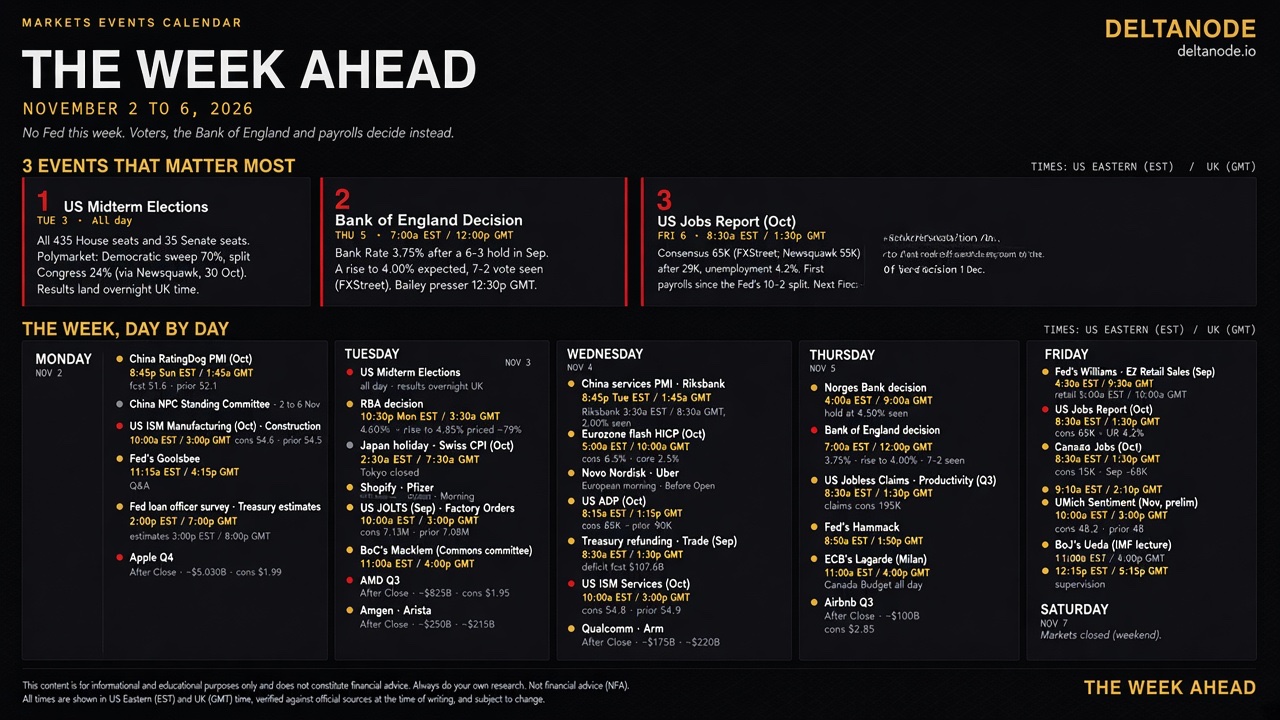
📅 2. WEEK AHEAD: KEY EVENTS
🔴 HIGH-IMPACT EVENTS
🇺🇸 US Midterm Elections Tuesday, November 3 | All day
🏦 Bank of England Interest Rate Decision Thursday, November 5 | 7:00 AM ET / 12:00 PM GMT
🇺🇸 US October Jobs Report Friday, November 6 | 8:30 AM ET / 1:30 PM GMT
🍎 Apple Q4 Earnings Monday, November 2 | After market close
🟠 OTHER IMPORTANT EVENTS
• Monday–Wednesday: US ISM Manufacturing and Services PMIs. • Wednesday: Eurozone October Flash Inflation. • Tuesday–Wednesday: AMD, Arista Networks, Qualcomm and Arm earnings. • Wednesday: US Treasury Quarterly Refunding. • Tuesday: Reserve Bank of Australia interest-rate decision. • Wednesday: Riksbank interest-rate decision. • Friday: Canadian October Employment Report.
━━━━━━━━━━━━━━━━━━
📆 3. DAILY ECONOMIC CALENDAR
🇨🇳 MONDAY, NOVEMBER 2
China Manufacturing PMI – RatingDog 🕐 1:45 AM GMT • Forecast: 51.6 • Previous: 52.1
China's private manufacturing survey will provide another indication of industrial activity.
China NPC Standing Committee 📅 November 2–6 | All day
China's top legislative body meets. The draft agenda reportedly contains no fiscal measures, including changes to the debt quota.
⚡ US ISM Manufacturing PMI – October 🕒 3:00 PM GMT • Forecast: 54.6 • Previous: 54.5 • Prices Paid Forecast: 77.0 • Previous: 77.9
A reading above 50 indicates manufacturing expansion. The prices-paid component will be particularly important for inflation expectations.
US Construction Spending – September 🕒 3:00 PM GMT
September construction activity figures will be released alongside ISM.
Fed's Austan Goolsbee 🕓 4:15 PM GMT
The Chicago Fed President moderates a Q&A with Andréa Maechler of the Bank for International Settlements. This is not necessarily a monetary-policy speech.
Fed Senior Loan Officer Survey – Q3 🕖 7:00 PM GMT
Important for understanding whether US banks are tightening or loosening lending standards.
US Treasury Financing Estimates 🕗 8:00 PM GMT
The Treasury releases its borrowing estimates ahead of Wednesday's quarterly refunding announcement.
💻 EARNINGS
⚡⚡⚡ AAPL | Apple After market close | Approx. $5.03 trillion market cap
Key things to watch: • Revenue guidance: 9%–11% growth. • Implied revenue: approximately $111.7B–$113.7B. • EPS consensus: $1.99. • First earnings call under CEO John Ternus. • Earnings call: 10:00 PM GMT.
━━━━━━━━━━━━━━━━━━
🇺🇸 TUESDAY, NOVEMBER 3
⚡⚡⚡ US Midterm Elections 📅 All day
All 435 House seats, 35 Senate seats and 36 governorships are on the ballot. Results will arrive throughout Tuesday night ET and into Wednesday morning in Europe.
Political uncertainty could influence fiscal policy, regulation, government spending and market sentiment.
🏦 Reserve Bank of Australia – Interest Rate Decision 🕒 3:30 AM GMT • Current rate: 4.60%. • Market-implied probability of a hike to 4.85%: approximately 79%. • September inflation: 4.3%.
Governor Michele Bullock's press conference follows one hour later.
Swiss CPI – October 🕢 7:30 AM GMT
Previous: • Monthly inflation: 0.0%. • Annual inflation: 1.0%.
US JOLTS Job Openings – September 🕒 3:00 PM GMT • Forecast: 7.13 million. • Previous: 7.08 million.
An important labour-market indicator ahead of Friday's payrolls.
US Factory Orders – September 🕒 3:00 PM GMT • Forecast: +1.2%. • Previous: +0.1%.
Bank of Canada Governor Tiff Macklem 🕓 4:00 PM GMT
Macklem and Senior Deputy Governor Carolyn Rogers appear before the House of Commons Finance Committee. A Senate committee appearance follows Thursday.
🇯🇵 Japan: Market Holiday Tokyo markets closed for Culture Day.
💻 EARNINGS
⚡⚡⚡ AMD | Advanced Micro Devices After market close | Approx. $825B market cap • EPS consensus: $1.95. • Watch data-centre chip sales and AI demand. • Call: 10:00 PM GMT.
⚡⚡ AMGN | Amgen After market close | Approx. $250B • EPS consensus: $5.79. • Focus: sales growth of newer drugs. • Call: 9:30 PM GMT.
⚡⚡ ANET | Arista Networks After market close | Approx. $215B • EPS consensus: $1.08. • Focus: AI networking orders from major cloud providers. • Call: 9:30 PM GMT.
SHOP | Shopify Before market open | Approx. $205B • Focus: merchant sales volume ahead of the holiday quarter. • Call: 1:30 PM GMT.
PFE | Pfizer Morning | Approx. $175B • EPS consensus: $0.73. • Focus: confirmation of 2026 guidance. • Call: 3:00 PM GMT.
━━━━━━━━━━━━━━━━━━
🇪🇺 WEDNESDAY, NOVEMBER 4
China Services PMI – RatingDog 🕐 1:45 AM GMT • September previous: 51.6.
⚡⚡ Eurozone Flash Inflation – October 🕙 10:00 AM GMT • Headline forecast: 3.9%. • Previous: 3.8%. • Core forecast: 2.5%.
France and Italy have already reported October inflation of 3.8% and 5.6%, respectively, both above expectations.
This is the first major eurozone inflation reading since the ECB held rates at 2.50% last week.
Riksbank Interest Rate Decision 🕣 8:30 AM GMT • Current rate: 1.75%. • Expected rate: 2.00%.
Markets broadly expect a 25-basis-point increase.
⚡ US ADP Employment – October 🕐 1:15 PM GMT • Forecast: +65,000 jobs. • Previous: +90,000.
A preliminary indicator ahead of Friday's official employment report.
⚡⚡ US Treasury Quarterly Refunding 🕜 1:30 PM GMT
The Treasury announces the composition and size of upcoming bond auctions.
Barclays expects no changes to auction sizes, with the 10-year yield near 4.93%.
US Trade Balance – September 🕜 1:30 PM GMT • Forecast deficit: $107.6B. • Previous deficit: $105.6B.
US S&P Global Services PMI – Final 🕝 2:45 PM GMT • Previous flash composite reading: 57.6.
⚡⚡ US ISM Services PMI – October 🕒 3:00 PM GMT • Forecast: 54.8. • Previous: 54.9.
Services-sector selling prices in the S&P Global flash survey recorded their fastest increase since August 2022.
💻 EARNINGS
⚡ ARM | Arm Holdings After market close | Approx. $220B • EPS consensus: $0.48. • Focus: data-centre chip royalty revenue. • Call: 10:00 PM GMT.
⚡ NVO | Novo Nordisk European morning | Approx. $175B • Focus: weight-loss drug sales and competition from cheaper alternatives. • EPS consensus: $0.73 (US-listed shares).
⚡ QCOM | Qualcomm After market close | Approx. $175B • EPS consensus: $2.17. • Focus: smartphone chip sales and December-quarter guidance. • Call: 9:45 PM GMT.
UBER | Uber Before market open | Approx. $135B • Focus: trip growth and robotaxi partnerships. • Call: 1:00 PM GMT.
━━━━━━━━━━━━━━━━━━
🇬🇧 THURSDAY, NOVEMBER 5
⚡⚡⚡ Bank of England Interest Rate Decision 🕛 12:00 PM GMT
• Current Bank Rate: 3.75%. • Expected rate: 4.00%. • Previous September vote: 6–3 to hold. • Current market consensus: 7–2 in favour of a hike.
The Monetary Policy Report will be released alongside the decision.
Governor Andrew Bailey Press Conference 🕧 12:30 PM GMT
Bailey explains the decision and the Bank's updated economic forecasts.
Norges Bank Interest Rate Decision 🕘 9:00 AM GMT • Current rate: 4.50%. • Expected: Hold.
⚡ US Initial Jobless Claims 🕜 1:30 PM GMT • Forecast: 195,000. • Previous: 194,000.
US Productivity and Unit Labour Costs – Q3 🕜 1:30 PM GMT
The first Q3 estimate arrives after productivity increased 1.4% in Q2. Productivity is particularly relevant given the Fed's recent comments about strong productivity growth.
Fed's Beth Hammack 🕜 1:50 PM GMT
The Cleveland Fed President speaks after dissenting in favour of a rate increase at the October Fed meeting.
🇨🇦 Canada Federal Budget 📅 All day
Ottawa releases its federal budget one week after the Bank of Canada's decision.
ECB President Christine Lagarde 🕓 4:00 PM GMT
Lagarde speaks in Milan following Wednesday's eurozone inflation report.
💻 EARNINGS
ABNB | Airbnb After market close | Approx. $100B • EPS consensus: $2.85. • Focus: Q4 booking trends. • Call: 10:00 PM GMT.
━━━━━━━━━━━━━━━━━━
🇺🇸 FRIDAY, NOVEMBER 6
⚡⚡⚡ US Nonfarm Payrolls – October 🕜 1:30 PM GMT
• Forecast: +65,000 jobs. • Alternative Newsquawk estimate: +55,000. • Previous: +29,000. • Unemployment forecast: 4.2%.
This is arguably the most important economic release of the week. Employment strength or weakness could significantly change expectations for the Fed's December decision.
🇨🇦 Canada Employment Report – October 🕜 1:30 PM GMT • Forecast: +15,000 jobs. • Previous: -68,000.
Released simultaneously with US payrolls.
Fed's John Williams 🕤 9:30 AM GMT
The New York Fed President and permanent FOMC voter speaks ahead of the payrolls release.
Eurozone Retail Sales – September 🕙 10:00 AM GMT • Forecast: +0.6% year-on-year. • Previous: +0.8%.
Fed's Alberto Musalem 🕑 2:10 PM GMT
The St. Louis Fed President recently indicated that interest rates may need to rise again soon.
University of Michigan Consumer Sentiment – November Preliminary 🕒 3:00 PM GMT • Forecast: 48.2. • Previous: 48.0. • Previous year-ahead inflation expectations: 4.7%.
Bank of Japan Governor Kazuo Ueda 🕓 4:00 PM GMT
Ueda delivers the IMF's Michel Camdessus Central Banking Lecture in Washington.
Fed Vice Chair Michelle Bowman 🕔 5:15 PM GMT
Discusses bank supervision and regulation at the University of Mississippi.
━━━━━━━━━━━━━━━━━━
🎯 4. THE THREE EVENTS THAT MATTER MOST
1️⃣ US Midterm Elections – Tuesday
The election results could influence the future direction of fiscal spending, taxation, regulation and government policy.
Watch: • Congressional balance of power. • Potential changes in fiscal policy. • Market reaction to political uncertainty.
2️⃣ Bank of England – Thursday
A possible 25-basis-point hike to 4.00% would signal continued inflation concerns.
Watch: • Actual rate decision. • Voting split. • Bailey's comments. • Updated inflation and growth forecasts.
3️⃣ US Nonfarm Payrolls – Friday
With the Fed divided over its next move, employment data becomes particularly important.
Watch: • Payroll growth against the 55K–65K estimates. • Unemployment rate against 4.2%. • Wage growth. • Revisions to previous employment figures.
A stronger-than-expected labour market could reinforce expectations of further tightening, while weaker employment could ease rate pressure.
━━━━━━━━━━━━━━━━━━
🔍 5. DELTANODE: WHAT MARKETS SHOULD WATCH
This week's events create several important cross-market connections.
💵 US Dollar (DXY) A stronger employment report or hawkish Fed commentary could support the dollar. Weaker data could ease dollar strength.
📈 US Treasury Yields The 10-year yield near 4.93% is a critical macro variable. Further increases could pressure technology valuations, growth stocks and risk assets.
🥇 Gold Gold remains sensitive to real yields, dollar strength and geopolitical uncertainty. Watch the reaction to the Fed repricing and employment data.
📊 US Equities Apple, AMD, Arista, Arm and Qualcomm will provide another reading on AI infrastructure demand. Revenue growth, margins, capex and forward guidance matter more than headline EPS alone.
₿ Bitcoin & Crypto Bitcoin could react to: • DXY and Treasury yield movements. • Fed rate expectations. • US employment data. • Institutional risk appetite. • Broader equity market volatility.
The Treasury refunding announcement is also worth watching because bond supply and demand can influence yields and broader financial conditions.
━━━━━━━━━━━━━━━━━━
⚠️ FINAL TAKEAWAY
November starts with a complicated macro environment: resilient economic growth, elevated inflation, a divided Federal Reserve, rising Treasury yields and heavy AI infrastructure spending.
The most important trading windows are Tuesday's US elections, Thursday's Bank of England decision and Friday's US payrolls.
For this week, focus on the relationship between DXY, US 2Y/10Y yields, equity breadth, gold and Bitcoin rather than reacting to individual headlines.
The objective is to understand how capital is moving across markets, not to predict every event.
Δ DELTANODE | Connect the data. Understand the market.